How to Plan a Whole House Renovation Budget
Master how to plan a whole house renovation budget with realistic cost tiers, contingency tips, and phasing strategies. Call 8334393727 for help.
By Alexia Mabel
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
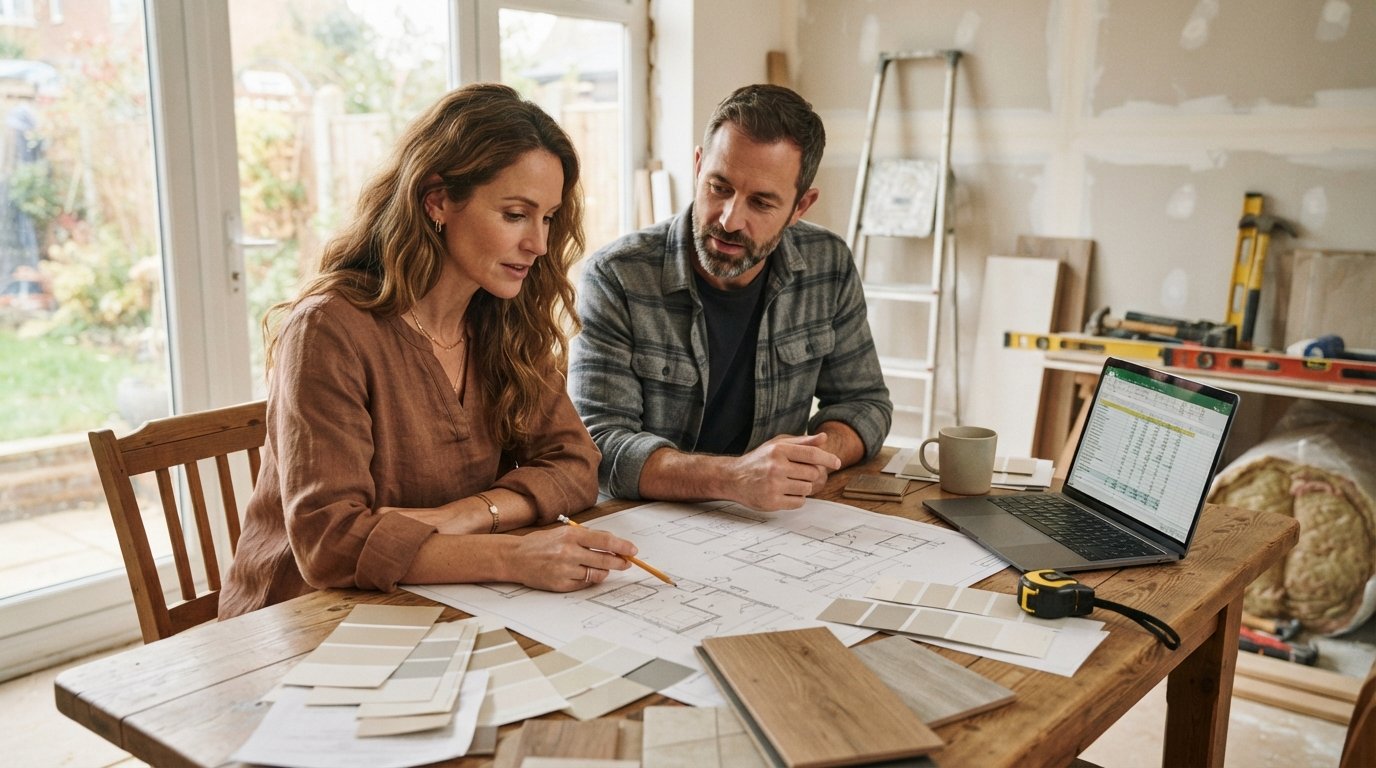
A whole house renovation is one of the largest financial commitments a homeowner will ever make, and the difference between a smooth project and a financial nightmare almost always comes down to one thing: the budget. According to industry data, a significant share of renovation projects run over budget, often by 10 to 30 percent, and the homeowners who stay in control are the ones who plan before they swing a hammer. Whether you are updating a 1970s ranch, restoring a historic property, or gutting a fixer-upper, learning how to plan a whole house renovation budget is the single most valuable skill you can develop before work begins.
This guide walks you through a practical, step-by-step approach to building a renovation budget that reflects real-world costs, protects you from surprise bills, and keeps your project on track from the first contractor call to the final walkthrough.
Start With a Realistic Total, Not a Wish List
Most homeowners begin with a number they hope to spend, then try to fit the project into it. That approach fails because renovation costs are driven by scope, materials, labor, and local market conditions, not by what feels comfortable. A better method is to work backward: research what your intended scope actually costs in your area, then decide whether you can afford that scope or need to phase it.
Whole house renovations typically fall into three broad tiers. A cosmetic refresh (paint, flooring, light fixtures, minor updates) may run $50 to $100 per square foot. A mid-range renovation that touches kitchens, bathrooms, and systems often lands between $100 and $200 per square foot. A full gut renovation with structural changes, new mechanicals, and high-end finishes can exceed $200 to $400 per square foot, depending on your region and material selections. A 2,000 square foot home in the middle tier, for example, could realistically cost $200,000 to $400,000 before contingencies.
These ranges are not meant to frighten you; they are meant to ground you. Once you have a realistic total, you can make informed trade-offs. If the number is higher than you expected, you can reduce scope, phase the work over several years, or adjust your finish level rather than discovering the shortfall mid-project when walls are already open.
Break the Project Into Cost Categories
A whole house budget is not one number; it is a collection of line items that each behave differently. Separating them helps you see where money actually goes and where you have room to negotiate or cut. Most renovation budgets should include the following major categories:
- Design and permits: Architectural drawings, engineering, permit fees, and inspections, typically 5 to 15 percent of total project cost.
- Structural and demolition: Removing walls, reinforcing framing, foundation work, and debris removal.
- Mechanical systems: HVAC, plumbing, and electrical upgrades, which are often the most underestimated line items in older homes.
- Interior finishes: Flooring, drywall, paint, trim, cabinetry, countertops, and fixtures.
- Exterior and landscaping: Roofing, siding, windows, doors, decks, and any yard restoration needed after construction.
Once these categories are laid out, assign a percentage of your total budget to each. A common starting split is roughly 30 percent to finishes, 25 percent to mechanical and structural work, 20 percent to labor and installation, 15 percent to design and permits, and 10 percent to contingency. Your split will shift depending on the condition of the home and the goals of the project, but having a baseline keeps you from overspending in one area without realizing it.
Get Multiple Contractor Quotes Before You Commit
Your budget is only as accurate as the quotes behind it. A single estimate from one contractor is not a budget; it is one opinion. To build a reliable number, request at least three detailed quotes from licensed, insured contractors who have completed similar projects in your area. When comparing quotes, look beyond the bottom line: review the scope of work, the materials specified, the timeline, and what is excluded.
This is where a service like Homes.Contractors becomes genuinely useful. The platform connects homeowners with pre-vetted local contractors and lets you request multiple free, no-obligation quotes from a single project request, which makes it far easier to compare pricing and scope side by side. You can also review service directories, cost guides, and FAQ resources to understand what a fair price looks like before you talk to anyone.
Watch for quotes that are dramatically lower than the rest. They usually signal missing scope, low-grade materials, or a contractor who plans to charge for changes later. A quote that is 40 percent below the others is not a bargain; it is a warning sign.
Build In a Contingency Fund You Will Actually Keep
Every renovation reveals surprises once walls come down. Hidden water damage, outdated wiring, asbestos, or a structural issue that was invisible during the walkthrough can add thousands of dollars in a single day. A contingency fund is not optional; it is the difference between finishing your project and running out of money halfway through.
Standard advice is to set aside 10 to 20 percent of your total budget for contingencies. For older homes or projects involving major systems, lean toward 20 percent or more. The key is to treat this money as untouchable. It is not a slush fund for upgraded countertops or a nicer front door; it exists solely to absorb the unexpected.
If you reach the end of the project without using the full contingency, that is a win, not a waste. You can then decide whether to apply the remaining funds to a future phase or simply return them to savings.
Decide What to Phase and What to Prioritize
Very few homeowners can or should do everything at once. Phasing a renovation is a legitimate strategy, not a compromise, and it can dramatically reduce financial strain while still delivering the home you want. The trick is to phase intelligently: handle structural, mechanical, and safety-related work first, then move to cosmetic upgrades.
A sensible phasing order often looks like this:
- Roof, foundation, and structural repairs, so the home is sound and watertight.
- HVAC, plumbing, and electrical updates, since these are easiest to do while walls are open.
- Kitchens and bathrooms, which deliver the highest daily impact and resale value.
- Flooring, paint, and trim throughout the rest of the home.
- Exterior finishes, landscaping, and outdoor living spaces.
Phasing does come with trade-offs. Doing work in stages can cost more overall than a single coordinated project, and some tasks (like running new wiring) are far cheaper when done alongside other work. If you phase, plan the sequence carefully so you are not reopening finished walls later.
Track Spending and Communicate Constantly
A budget is a living document. Once work begins, you need a simple system to track what has been spent, what is committed, and what remains. A basic spreadsheet with columns for category, estimated cost, actual cost, and variance is enough for most homeowners. Review it weekly with your contractor so small overruns are caught early rather than discovered at the end.
Communication matters just as much as bookkeeping. Establish upfront how change orders will be handled, who approves them, and how they affect the schedule and price. Any change, even a small one, should be documented in writing before work proceeds. This protects both you and the contractor and prevents the awkward, expensive disputes that derail projects.
If you want to reduce costs without sacrificing quality, there are legitimate strategies worth exploring, such as keeping plumbing fixtures in place, choosing mid-range materials in low-visibility areas, and doing some demolition or painting yourself. For a deeper look at where the real savings are, our guide on cost saving strategies for a whole house renovation breaks down which trade-offs pay off and which ones backfire.
Plan for the Costs After Construction
Many homeowners forget that the budget does not end when the last contractor leaves. There are often post-renovation costs that catch people off guard, including final cleaning, landscaping restoration, furniture replacement for rooms that no longer fit the old layout, and higher property taxes if your assessment increases. In some cases, insurance premiums also adjust after major updates.
Set aside a small post-project fund, even a few thousand dollars, to cover these finishing touches. It is far less stressful to plan for them than to realize your new kitchen has no chairs and your savings account is empty.
Finally, remember that a well-planned budget is not about spending the least; it is about spending intentionally. When you know what each part of your renovation should cost, you can negotiate from strength, avoid panic decisions, and finish with a home that reflects your goals rather than your compromises. Take the time to plan the numbers first, and the rest of the project becomes dramatically easier to manage. PlanRemodel
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.