Planning For Future Home Improvements: Budget Tips
Planning for future home improvements budget tips help you avoid surprise bills and protect your home's value. Build a realistic plan with these strategies.
By Adnan Nazir
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
Your home is likely your largest investment, and maintaining or upgrading it takes more than good intentions. It requires a plan. Whether you are dreaming of a kitchen remodel, bracing for a roof replacement, or simply want to avoid surprise repair bills, the difference between a smooth project and a financial headache often comes down to how you prepare. Planning for future home improvements budget tips are not just about saving money; they are about gaining control, reducing stress, and making smarter decisions that protect your property's value for years to come.
Most homeowners underestimate costs by 20 to 30 percent, according to industry surveys. That gap often leads to abandoned projects, compromised quality, or high-interest debt. The good news is that you can close that gap with a disciplined approach. This guide walks you through practical strategies to build a realistic budget, anticipate hidden expenses, and time your projects for maximum return. Along the way, we will highlight how to leverage free resources to get competitive quotes without pressure.
Start With A Home Improvement Master Plan
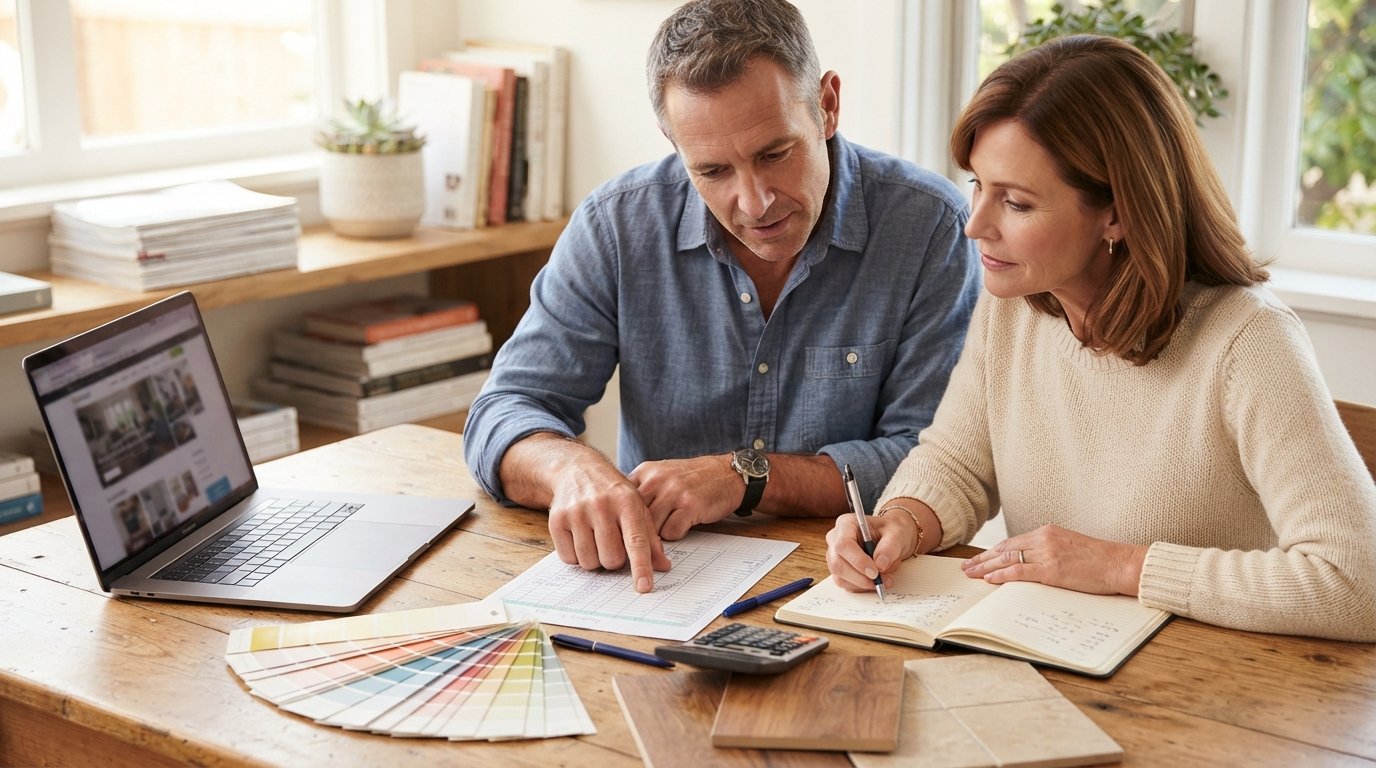
Before you pick paint colors or browse flooring samples, step back and look at your home as a whole. A master plan is a simple document that lists every improvement you might want to make over the next five to ten years. It does not have to be fancy. A spreadsheet or a notebook works fine. The goal is to prioritize needs versus wants, and to sequence projects logically.
For example, replacing windows might come before interior painting, because window installation can damage walls. Fixing a leaky roof should always precede attic insulation. By mapping out dependencies, you avoid doing the same work twice. Your master plan should also include a rough timeline. Are you planning to sell in three years? Then focus on high-ROI updates like siding or minor kitchen refreshes. Staying put for a decade? You can invest in more personal choices like a sunroom or custom built-ins.
Once your master plan is in place, you can assign a preliminary budget range to each project. Use online cost guides or request free quotes from local contractors to get accurate numbers. A platform like FreeQuotes.Contractors lets you submit one request and receive multiple bids from pre-vetted professionals, which gives you a realistic baseline without any obligation. That early research prevents you from anchoring your budget to outdated or unrealistic figures.
Build A Dedicated Home Improvement Fund
Relying on credit cards or emergency savings for planned upgrades is a recipe for financial strain. Instead, treat your home improvement goals like a separate financial bucket. Open a high-yield savings account specifically for home projects and automate a monthly transfer. Even small amounts add up: $200 a month becomes $2,400 in a year, enough to cover a minor bathroom refresh or a new water heater.
How much should you set aside? A common rule of thumb is 1 to 2 percent of your home's value annually for maintenance and repairs. On a $300,000 home, that is $3,000 to $6,000 per year. If you are planning a major remodel, you will need to save more aggressively. Break the goal into monthly milestones. For a $30,000 kitchen remodel in two years, you need to save $1,250 per month. Seeing that number makes the goal concrete and helps you adjust other spending.
Keep this fund separate from your emergency savings. Emergency funds cover unexpected events like a flooded basement or a broken furnace. Your home improvement fund covers planned projects. Mixing them can leave you unprepared when a real crisis hits. If you must dip into your improvement fund for an emergency, replenish it as soon as possible.
Account For The Hidden Costs Of Remodeling
Even the most detailed estimate can miss expenses that pop up during construction. Hidden costs are the number one reason budgets blow up. Common culprits include permitting fees, design revisions, temporary housing, and disposal of old materials. Older homes often hide problems behind walls: outdated wiring, asbestos, or mold. You cannot predict everything, but you can plan for the unknown.
Financial experts recommend adding a contingency fund of 10 to 20 percent on top of your project estimate. For a $20,000 bathroom remodel, that means having an extra $2,000 to $4,000 available. This buffer is not wasted money; it is insurance against delays and surprises. If you do not use it, you can roll it into the next project or back into savings.
Here are the most overlooked costs to include in your budget:
- Permits and inspection fees: These vary by municipality and can range from $100 to over $1,000 for major work.
- Design and engineering fees: Architects, structural engineers, or interior designers may charge hourly or a percentage of project cost.
- Dumpster rental and debris removal: Especially for demolition-heavy projects.
- Sales tax on materials: Often forgotten, but can add hundreds of dollars.
- Temporary relocation: If your kitchen or bathroom will be unusable for weeks, factor in hotel or dining costs.
When you request quotes, ask contractors whether their estimate includes these items. A transparent contractor will break down costs clearly. If a bid seems too low, it probably omits something important. Use the quote comparison process to identify gaps and ask questions before you sign anything.
Time Your Projects For Better Pricing
Contractor availability and material prices fluctuate throughout the year. In many regions, spring and summer are peak seasons for roofing, painting, and outdoor projects. Demand is high, and so are prices. Scheduling your project in the off-season (late fall or winter for exterior work) can sometimes secure lower rates and more attentive service. Interior projects like flooring or painting can be done year-round, but January and February are often slower for contractors, giving you more negotiating power.
Material costs also follow seasonal trends. Lumber prices tend to rise in spring when construction ramps up. Solar panel installation may be cheaper in winter when installers are less busy. If your project requires specialty materials, order them early to lock in current prices and avoid delivery delays. Keep an eye on sales at home improvement stores, but do not compromise quality for a discount.
Another timing strategy is to bundle projects. If you need a new roof and solar panels, doing them together can save on labor and equipment rental. The same goes for kitchen and flooring updates: tearing out cabinets and flooring at the same time reduces labor hours. However, bundling only works if your budget can handle the combined cost. Otherwise, sequence projects to spread out expenses.
Leverage Free Quotes To Refine Your Budget
One of the most effective budget tips is to gather multiple quotes before committing to a project. Not only does this help you find the best price, but it also educates you on what the job actually entails. Contractors may suggest different approaches or materials, and those conversations reveal line items you might have missed. The more quotes you collect, the clearer your budget becomes.
Start by defining your project scope in writing. Include dimensions, materials you prefer, and any specific requirements. Then reach out to at least three contractors. Be wary of any bid that is significantly lower than the others; it could signal cut corners or hidden fees. Similarly, a very high bid does not always mean better quality. Look for a detailed breakdown of labor, materials, permits, and timeline.
If you are planning energy-efficient upgrades like insulation, windows, or solar, you may qualify for tax credits or rebates. Our guide on contractors for energy-saving home improvements explains how to find qualified installers and maximize incentives. Factoring these savings into your budget can make a project more affordable than you think.
Prioritize Projects With High Return On Investment
Not all home improvements are created equal. If your goal is to build long-term value, focus on projects that recoup a significant portion of their cost at resale. According to national remodeling impact studies, garage door replacement, manufactured stone veneer, and minor kitchen remodels consistently deliver high returns. Major upscale projects like a master suite addition or high-end kitchen remodel may bring joy, but they often recoup less than 60 percent of their cost.
Maintenance projects are less glamorous but equally important. A new roof, updated HVAC system, or fresh exterior paint protects your home from costly damage and signals to buyers that the property is well cared for. These improvements may not increase your home's value dollar for dollar, but they preserve it. Skipping maintenance can lead to much larger expenses down the road.
When budgeting, categorize projects into three tiers: must-do (safety and structural), should-do (efficiency and value), and want-to-do (aesthetic and personal). Fund the must-do items first. Then allocate remaining savings to should-do projects. Want-to-do projects come last, and only if your budget allows. This hierarchy ensures you never neglect critical repairs in favor of a cosmetic upgrade.
Plan For Financing Before You Need It
Even with diligent saving, some projects require financing. The key is to arrange it before you are under pressure. Explore options like home equity loans, HELOCs, cash-out refinancing, or contractor financing. Each has pros and cons. A HELOC offers flexibility and low interest rates but requires equity. Contractor financing may be convenient but often carries higher rates. Personal loans are unsecured but can have higher interest than secured options.
Get pre-approved for a loan or line of credit before you start collecting bids. This gives you a clear spending limit and strengthens your negotiating position. It also prevents you from accepting a rushed financing offer from a contractor. Remember that borrowing costs should be included in your overall project budget. A 5 percent interest rate on a $20,000 loan adds $1,000 over a two-year repayment period.
If you are planning a major renovation, consider consulting a financial advisor. They can help you balance home improvement goals with retirement savings, emergency funds, and other financial priorities. Avoid tapping into retirement accounts or using high-interest credit cards unless absolutely necessary. Your future self will thank you.
Track Spending And Adjust In Real Time
A budget is a living document. Once your project begins, track every expense against your estimate. Use a simple spreadsheet or a budgeting app. Categorize costs by labor, materials, permits, and contingency. If you notice a category running over, address it immediately. Maybe you can downgrade a material choice or postpone a non-essential feature. Early intervention keeps small overruns from becoming big problems.
Communication with your contractor is critical. Ask for weekly updates on spending and progress. If change orders arise, get them in writing with a clear cost breakdown before work proceeds. Verbal agreements lead to disputes. A good contractor will appreciate your diligence and work with you to stay on budget.
Finally, review your budget after the project is complete. What went well? Where did you overspend? Use those lessons to refine your master plan and savings strategy for the next project. Over time, you will become a more confident and savvy homeowner, ready to tackle improvements without financial fear.
Planning for future home improvements is a marathon, not a sprint. By creating a master plan, building a dedicated fund, accounting for hidden costs, timing projects wisely, and leveraging free quotes, you put yourself in a position of strength. Your home will thank you with lasting value, comfort, and peace of mind.