Financing a Home Improvement Project With Bad Credit
Bad credit does not block home improvement financing. Explore loans, HELOCs, and contractor options that still approve you and protect your budget.
By Chelsea Kris
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
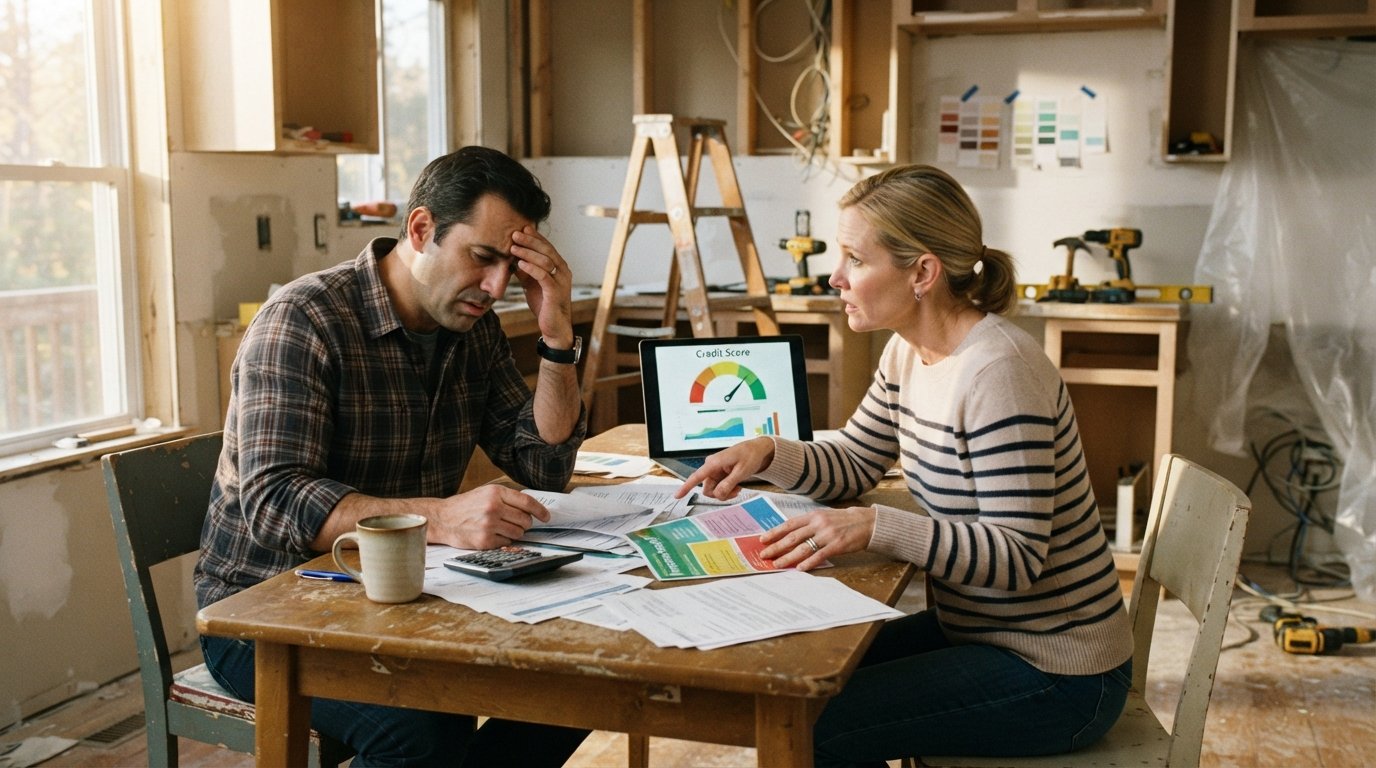
Your roof is leaking, your kitchen is stuck in 1985, or you simply need more space, and the estimate you just received is far beyond what you can pay in cash. Then you remember the credit score sitting in the low 500s or 600s, and the familiar knot tightens in your stomach. Here is the reality check that matters: a damaged credit score does not lock you out of home improvement financing. It changes the menu of options, the interest rates, and the strategy you should use, but it does not end the conversation. Thousands of homeowners with imperfect credit complete roofing replacements, bathroom remodels, and HVAC installations every year by choosing the right funding path and preparing their application correctly.
This guide walks through the realistic financing routes available when your credit is less than perfect, how to compare them without getting buried in fees, and how to position yourself so lenders see you as a reasonable risk rather than an automatic denial. It also covers how to keep the project itself on budget, because the fastest way to turn a manageable loan into a financial disaster is to let contractor costs spiral out of control.
Why Your Credit Score Matters Less Than You Think
Lenders use credit scores as one input among many, not as a single pass or fail gate. A score of 580 will not qualify you for the same terms as a score of 780, but it can still qualify you for several products. The key is understanding what each lender actually cares about. Some weigh income stability heavily. Others focus on the loan to value ratio of your home. Still others specialize in borrowers with past credit trouble and price their loans accordingly. When you understand this, you stop treating your score as a verdict and start treating it as a variable you can work around.
It also helps to separate the two major buckets of home improvement financing: secured options, which use your home as collateral, and unsecured options, which rely on your signature and creditworthiness alone. Secured loans generally come with lower rates because the lender has something to recover if you default. Unsecured loans and credit cards carry higher rates but do not put your house at risk. Your choice between them depends on how much you are borrowing, how quickly you can repay, and how much risk you are willing to accept.
Before you apply anywhere, pull your credit reports from all three major bureaus. Errors are common, and a single inaccurate collection account can drag your score down by dozens of points. Disputing errors takes time, so start this step at least a month before you plan to apply. In the meantime, avoid opening new credit accounts and keep your existing balances low relative to their limits. These small moves can nudge your score upward enough to change which products you qualify for.
Financing Options That Work With Damaged Credit
The financing landscape for borrowers with bad credit is wider than most people assume. The trick is matching the product to your situation rather than applying for the first offer that appears in your mailbox. Here are the main categories worth considering, roughly in order from lowest cost to highest cost.
- Cash-out refinance: You replace your existing mortgage with a larger one and pocket the difference in cash. Rates are relatively low because the loan is secured by your home, but you need enough equity and a lender willing to work with your credit profile. This works best for large projects.
- Home equity line of credit (HELOC): A revolving line of credit secured by your home. You draw only what you need and pay interest only on the drawn amount. Credit requirements are stricter than for a cash-out refinance, but some credit unions offer HELOCs to borrowers in the 600s.
- FHA 203(k) loan: A government-backed mortgage that bundles the home purchase or refinance with renovation costs. It is designed specifically for fixer-uppers and has more flexible credit requirements than conventional loans.
- Personal loans: Unsecured installment loans from banks, credit unions, or online lenders. Rates are higher, but approval is faster and your home is not on the line. Best for smaller projects in the $5,000 to $25,000 range.
- Contractor-arranged financing: Some remodeling companies partner with lenders to offer financing at the point of sale. These programs often approve borrowers with lower scores because the contractor has a relationship with the lender.
- Credit cards with promotional APR: A 0 percent introductory rate for 12 to 18 months can work for small projects if you can pay the balance off before the promotional period ends. After that, the rate jumps sharply.
Each of these options carries trade-offs. A cash-out refinance replaces your entire mortgage, which means closing costs and a new long-term payment schedule. A HELOC gives you flexibility but often comes with a variable rate that can rise. A personal loan is simple and fast but expensive over long terms. Contractor financing is convenient, but you should always compare the offered rate against what you could get independently, because convenience sometimes carries a premium.
One additional path deserves mention: asking the contractor about a payment schedule tied to project milestones. Some remodelers will break a large job into phases, letting you pay for the bathroom now and the bedroom later. This is not technically financing, but it spreads the cash flow burden without adding interest. It works best when you have a clear written schedule and both sides agree on what triggers each payment.
How to Improve Your Approval Odds Before You Apply
Approval is not purely about your score. Lenders look at your debt to income ratio, your employment history, your cash reserves, and the size of the loan relative to your income. You can influence several of these factors in the weeks before you apply.
Start by calculating your debt to income ratio. Add up all your monthly debt payments, including the new loan you are seeking, and divide by your gross monthly income. Most lenders prefer this number to stay below 43 percent, and some will go higher for secured loans. If your ratio is too high, paying down a credit card balance or waiting for an installment loan to finish can make a meaningful difference.
Next, gather your documentation in advance. Lenders want proof of income, tax returns, bank statements, and sometimes a letter explaining past credit issues. A short, honest explanation of a past hardship (a medical emergency, a layoff, a divorce) can carry more weight than you expect, especially with credit unions and community banks that review applications manually rather than relying on an algorithm.
Consider adding a co-borrower. If a spouse, partner, or family member with stronger credit is willing to sign, your combined application may qualify for better terms. This is a significant commitment, so discuss it openly and put the agreement in writing, including who is responsible for repayment.
Finally, apply to more than one lender, but do it within a short window. Mortgage and auto loan inquiries within a 14 to 45 day period typically count as a single inquiry for scoring purposes. Personal loan inquiries are treated individually, so space those applications out and focus on lenders that pre-qualify you with a soft credit pull first.
Keeping the Project Itself Affordable
Financing is only half the battle. The other half is making sure the project does not balloon beyond what you borrowed. Home improvement costs are notorious for creeping upward once walls open up and hidden problems appear. A bathroom remodel that starts at $15,000 can easily reach $25,000 if you discover water damage, outdated wiring, or a failed subfloor.
The best defense is a detailed written estimate from each contractor you consider, with line items for labor, materials, permits, and a clearly stated contingency. Compare at least three bids before committing, and pay attention to what each one excludes. A low bid that omits permit fees or debris removal is not actually low. If you need help understanding how change orders affect your final bill, the guide on change orders in construction explains how to review and approve them without losing control of your budget.
Set aside a contingency fund of at least 10 to 20 percent of the project cost. If you are financing $20,000, borrow $22,000 to $24,000, or keep the extra amount available on a credit line. This buffer is what separates a smooth renovation from a mid-project crisis when the unexpected appears.
You should also verify every contractor before signing anything. Check licenses, insurance, and references, and get everything in writing. Homes.Contractors is a directory and referral platform, not a guarantor of any contractor's work, so independent verification is your responsibility. When you are ready to gather bids, you can request free quotes from pre-vetted local contractors and compare them side by side before making a decision.
Mistakes to Avoid When Credit Is Tight
The biggest mistake borrowers with bad credit make is accepting the first offer without comparing it. Predatory lenders target people who are anxious and uninformed, and the terms they offer can trap you in a cycle of high payments. Always read the annual percentage rate, not just the monthly payment, and check for origination fees, prepayment penalties, and balloon payments.
A second common mistake is borrowing more than the project requires. It is tempting to add a hot tub or upgrade to premium fixtures when you are already filling out loan paperwork, but every extra dollar increases your monthly obligation. Stick to the scope you actually need, and revisit the extras once the loan is paid down.
Third, do not ignore the impact of a new loan on your overall financial picture. A home improvement loan is a long-term commitment, often three to seven years or longer. Run the numbers in a budget spreadsheet before you sign, and make sure the payment fits comfortably alongside your mortgage, utilities, insurance, and savings goals. If it does not, scale back the project or wait until your credit improves.
Finally, avoid using high-interest credit cards for large projects unless you have a clear repayment plan. A $10,000 balance at 24 percent APR takes years to pay off if you only make minimum payments, and the interest can end up costing more than the project itself.
Financing a home improvement project with bad credit is a challenge, but it is not an impossible one. By understanding your options, preparing your application carefully, and keeping the project scope under control, you can move forward with the repairs or upgrades your home needs without waiting years for your credit to recover. Start by checking your credit reports, gathering a few contractor estimates, and exploring the lenders and programs that specialize in borrowers like you. The right combination of preparation and patience will get you there.
Learn more about Exterior Painting for guides, costs, and what to expect.
Compare Exterior Painting Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.