Budgeting for Home Renovation Contingencies and Unexpected Costs
Master budgeting for home renovation contingencies and unexpected costs to avoid surprise bills. Call 8334393727 for contractor quotes and expert guidance.
By Chelsea Kris
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
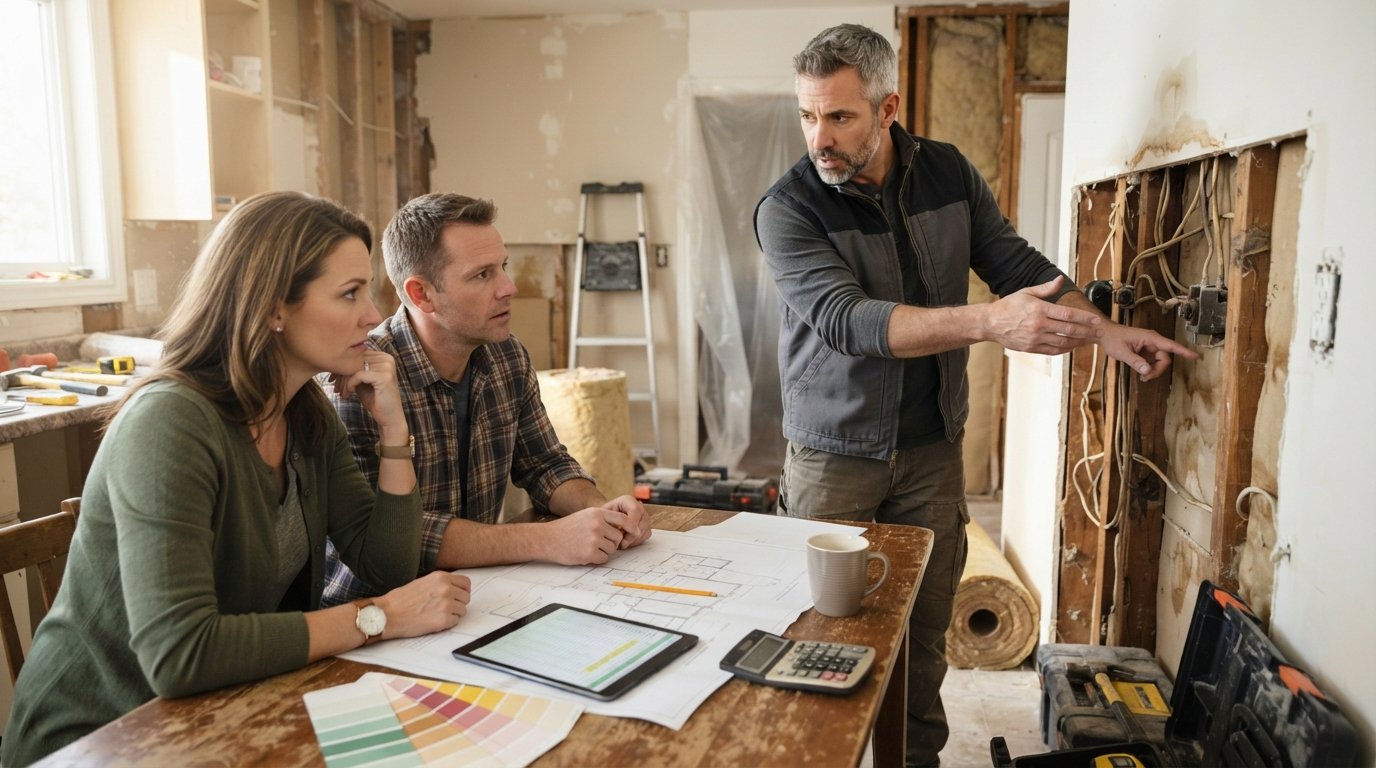
You have picked the paint colors, chosen the tile, and signed the contractor's estimate. The project feels fully mapped out until the crew opens a wall and finds water damage, outdated wiring, or a structural surprise that no inspection could predict. These moments are where renovation budgets either hold steady or spiral out of control. Budgeting for home renovation contingencies and unexpected costs is the single most effective way to protect your project, your savings, and your sanity when the unplanned inevitably happens.
The homeowners who navigate renovations successfully are rarely the ones who predicted every surprise. They are the ones who built financial breathing room into the plan before the first hammer swung. This guide walks through how much to set aside, where surprises typically hide, how to manage change orders, and how to keep your project moving when the numbers shift.
Why Renovation Budgets Break: The Real Cost of Surprises
Most renovation budgets fail for the same reason: they are built on the best-case scenario. A contractor's estimate reflects the visible scope of work, the conditions that can be assessed before demolition, and the materials specified at the time of bidding. It does not account for what is hidden behind drywall, beneath flooring, or inside walls that have not been opened in decades. According to industry surveys, a significant share of renovation projects exceed their original budgets, and the overruns are rarely caused by a single catastrophic event. They accumulate through dozens of small discoveries: a rotted subfloor here, a code violation there, a delayed material shipment that pushes labor costs higher.
Understanding this reality changes how you approach the entire budgeting process. Instead of treating the contractor's number as the final cost, treat it as the starting point. Your true budget includes the estimate plus a contingency reserve plus a plan for how you will handle costs that exceed even that reserve. Homeowners who adopt this mindset from day one are far less likely to find themselves making panicked decisions mid-project or abandoning the renovation halfway through.
The emotional dimension matters too. When unexpected costs appear, the stress is not just financial. It is the feeling of losing control over a project you thought was settled. A well-funded contingency turns a crisis into a manageable line item. You can approve the additional work, keep the schedule intact, and move forward without derailing the entire renovation.
How Much Contingency Should You Set Aside?
The most common recommendation in the renovation industry is to reserve 10 to 20 percent of your total project budget for contingencies. For straightforward cosmetic updates, such as painting, replacing fixtures, or installing new flooring in good condition, 10 percent is often sufficient. For projects that involve opening walls, altering plumbing or electrical systems, or working on older homes, 20 percent or more is prudent. If your home was built before 1980 and has not undergone major updates, consider setting aside 25 percent, because the likelihood of discovering outdated wiring, lead paint, asbestos, or failing pipes rises sharply with age.
Here is a simple framework for calculating your contingency based on project type:
- Cosmetic updates (painting, flooring, fixtures): 10 percent of project cost
- Single-room remodels (bathroom, kitchen without layout changes): 15 percent
- Major remodels with structural or system changes: 20 percent
- Older homes or full-house renovations: 25 percent or more
That percentage should be calculated on the total project cost, not just the contractor's labor and materials. Include permits, design fees, temporary housing if needed, and the cost of any items you plan to purchase yourself. A 20 percent contingency on a $50,000 kitchen remodel means setting aside $10,000 that you do not touch unless a genuine surprise arises. If the project finishes without needing it, you have a healthy reserve for the next maintenance issue or a well-earned upgrade.
Some homeowners make the mistake of folding the contingency into their visible budget, which effectively eliminates it. If you tell your contractor you have $60,000 to spend and allocate the full amount to visible line items, you have no reserve left. Instead, present a realistic scope of work that fits within $50,000 and hold the remaining $10,000 separately. This approach also gives you negotiating room when change orders arise, because you are not forced to accept the first price offered.
The Most Common Unexpected Costs in Home Renovation
Surprises in renovation tend to cluster around a few predictable categories. Knowing where they hide helps you anticipate them and ask better questions during the bidding process.
Hidden damage and deterioration. Water damage, mold, pest infestation, and rotted framing are among the most frequent discoveries once walls and floors are opened. These issues are often invisible during a standard home inspection and can add thousands of dollars in remediation and repair. If your contractor finds mold behind the shower wall, you will need to address it before proceeding, and that work is rarely included in the original estimate.
Code compliance and permitting issues. Older homes frequently have electrical, plumbing, or structural work that does not meet current building codes. Bringing that work up to standard is not optional; it is required for permits and inspections to pass. Unpermitted work from a previous owner can also surface, triggering retroactive permitting fees and corrections. In our guide on what happens if a contractor goes over budget, we explain how these situations affect your financial obligations and your options.
Material price increases and availability delays. Lumber, tile, appliances, and fixtures can fluctuate in price or become backordered. A delay of several weeks can push labor costs higher if your contractor's crew cannot work on other parts of the project. Locking in material prices early and ordering long-lead items before demolition begins can reduce this risk, but it cannot eliminate it entirely.
Design changes during construction. Homeowners often change their minds once they see the space taking shape. Moving a light switch, adding a cabinet, or upgrading a countertop mid-project creates change orders that add both cost and time. While some flexibility is reasonable, frequent changes are one of the fastest ways to drain a contingency fund.
Structural surprises. Load-bearing walls that were not identified, sagging floors, or foundation issues can require engineering assessments and significant additional work. These are the most expensive surprises, and they are also the hardest to predict without invasive investigation.
Change Orders: Managing Costs Without Stopping the Project
A change order is a formal document that modifies the original contract, specifying the additional work, the cost, and any impact on the schedule. Every unexpected cost that requires contractor labor or materials should be documented through a change order. Verbal agreements and handshake deals are a recipe for disputes later.
When a change order arrives, review it carefully before signing. Ask for a breakdown of labor and materials, and confirm whether the new work affects the project timeline. If the cost seems high, you have the right to request a second opinion or negotiate. A reputable contractor will not pressure you to approve immediately, though some changes (such as structural repairs) may be time-sensitive.
Your contingency fund is what allows you to approve necessary change orders without derailing the entire project. If the change order exceeds your remaining contingency, you have three options: reduce the scope of other parts of the project, find additional financing, or pause the project until you can fund the work. The worst choice is to proceed without a clear plan, hoping the numbers will work out.
For homeowners who want to compare contractor pricing before committing, platforms like FreeQuotes.Contractors allow you to request multiple quotes from local professionals, which can give you a clearer picture of fair market rates and help you avoid overpaying when surprises arise.
Building Your Contingency Fund: Practical Steps
Creating a contingency fund is not complicated, but it requires discipline. Start by calculating your total project cost, including permits, design, materials, labor, and any temporary living expenses. Then apply the appropriate contingency percentage based on the scope and age of your home. Set that money aside in a separate savings account so it is not accidentally spent on visible upgrades.
If you are financing the renovation through a loan or line of credit, check whether your lender allows you to borrow against a contingency reserve. Some renovation loans include a contingency line item, while others require you to fund it from your own savings. Understanding your financing options before the project begins helps you avoid scrambling for funds mid-construction.
Another practical step is to prioritize your must-haves versus your nice-to-haves. If the contingency gets depleted by a necessary repair, you can cut or delay the nice-to-haves to keep the project on track. This approach gives you flexibility without compromising the core function of the renovation.
Finally, communicate openly with your contractor about your budget and your contingency. A good contractor will help you identify potential risks early and suggest cost-effective alternatives when surprises arise. If your contractor dismisses your concerns or pressures you to spend beyond your means, that is a red flag worth taking seriously.
When to Walk Away or Pause
Not every surprise is manageable within your contingency, and not every project should continue at any cost. If the unexpected expenses exceed your reserve and your financing options, it may be wiser to pause the project, reassess, and return when you have a clearer financial picture. Pausing is not failure; it is a responsible decision that prevents you from taking on debt you cannot repay or compromising on workmanship to save money.
If you suspect your contractor is inflating costs or taking advantage of your situation, seek a second opinion from another licensed professional. Homeowners have rights when contractors act in bad faith, and understanding those rights can protect you from financial harm. Document everything, keep written records of all change orders, and do not hesitate to consult a legal professional if disputes escalate.
Renovation is inherently unpredictable, but that unpredictability does not have to derail your project. With a well-funded contingency, clear communication, and a willingness to adapt, you can navigate surprises confidently and finish with a home you love.